
Local and National Publishers Are Getting Opposite Advice on 2026 Revenue Strategy
Two industry surveys published within weeks of each other in early 2026 point in opposite directions, and both are right, for different publishers.
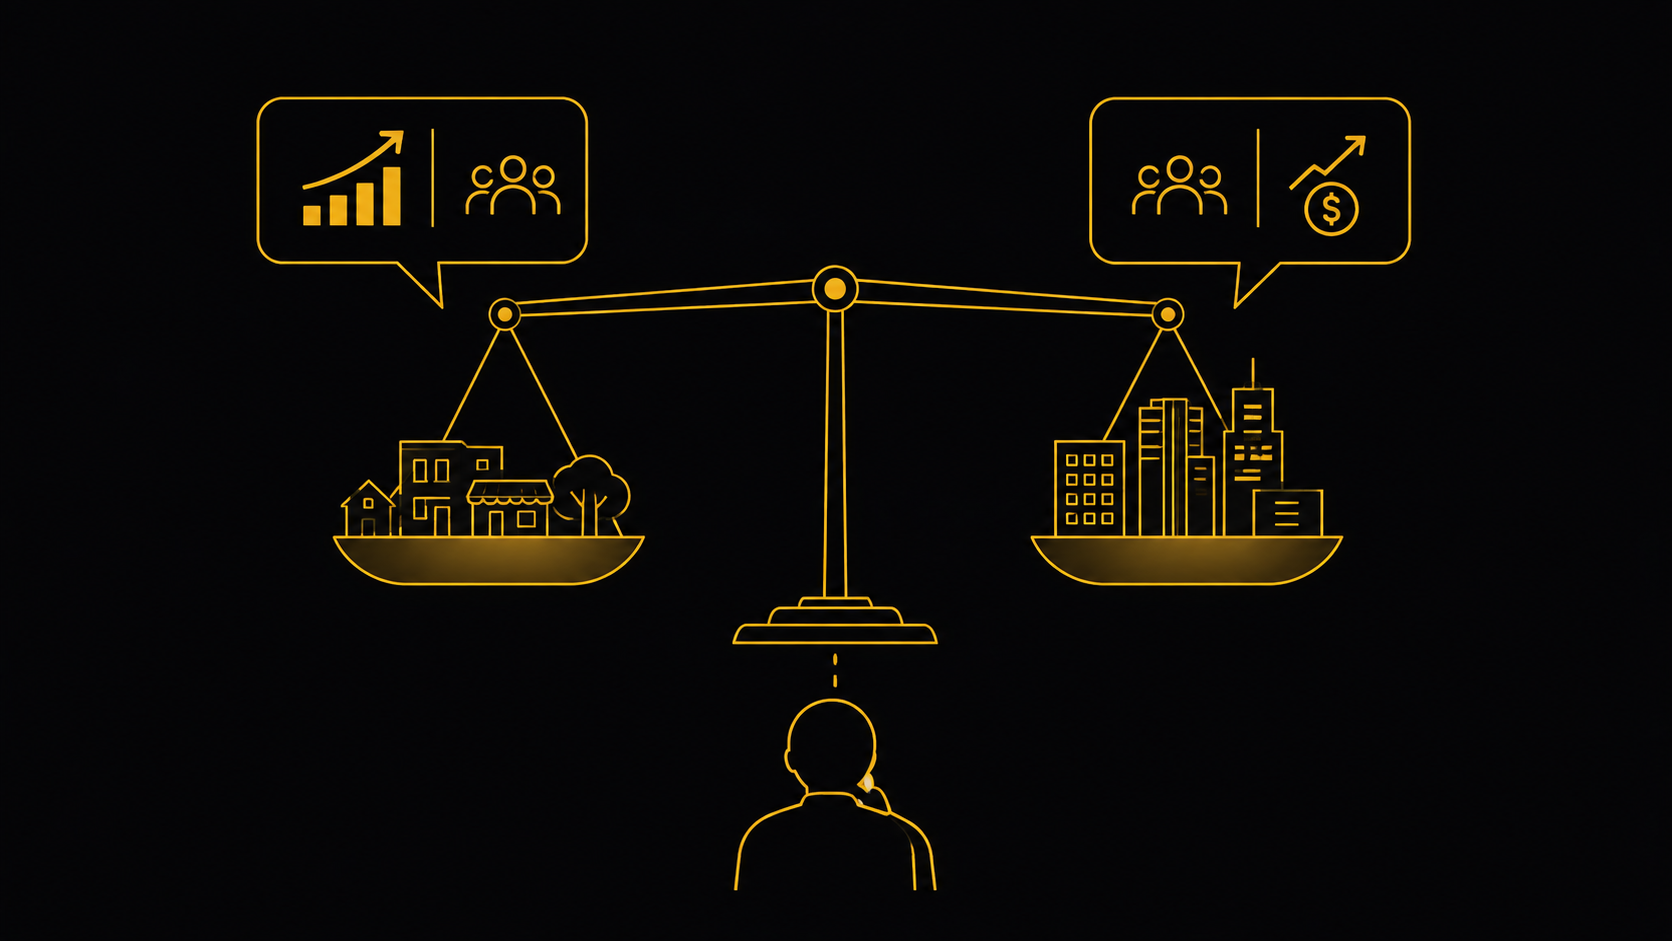
The Local Media Consortium's February 2026 survey found 72% of local publishers saw digital ad revenue up or flat in 2025, with 85% expecting the same in 2026. In the same survey, publishers citing subscription-related challenges as a top concern jumped 383% year-over-year. "Subscription growth has plateaued," said LMC CEO Fran Wills, "there has always been only a certain percentage of people in a market willing to pay."
Reuters Institute's Journalism, Media & Technology Trends 2026 report, based on 280 editors, CEOs, and digital leaders across 51 countries, found the opposite emphasis: 76% of commercial publishers named subscriptions and memberships their primary revenue focus for 2026, ahead of advertising at 64%.
Read only one of these reports and you get a confident, wrong-for-someone answer.
Why both are true at once
The LMC survey skews toward local and regional publishers. Reuters Institute's respondent base skews toward larger commercial and national outlets. These aren't contradictory findings about the same market. They're two different markets, each behaving rationally within its own constraints.
A local outlet in a market where most readers already get free information from Facebook groups, local TV, and word of mouth has a small addressable pool of people who'll ever pay for anything, subscription or otherwise. Ad revenue that's holding steady is a real, working option there, not a consolation prize. A national or large commercial outlet with a bigger, more geographically dispersed audience has a larger pool of people willing to pay for depth and authority they can't get from a local Facebook group, so subscriptions scale in a way they don't for a paper covering one county.
What determines which camp you're in
Three questions, not a size threshold:
Do you operate in a market with real competition for local attention, or close to a local information monopoly ? A monopoly market supports a harder paywall than a competitive one, because readers have fewer places to get the same story.
Is your audience defined by geography, or by topic and expertise? Geographic audiences are capped by population. Topic-based audiences (a trade publication, a specialist beat) can grow past any single market's ceiling.
Has your ad revenue actually been flat or growing over the past 12 months, checked in your own reporting rather than assumed from an industry average? The LMC number is real, but it's an average. Yours might not match it.
Small-scale counter-examples worth knowing about
The LMC-versus-Reuters split isn't a US-only pattern, and it isn't universal even at small scale. Dennik N in Slovakia and The Mill Media in the UK (a group of six local titles with roughly 13,000 paying subscribers combined) both built real subscription revenue at a size closer to the LMC survey's respondents than to a national outlet's. Neither result contradicts the LMC finding. It means the ceiling on subscription revenue at small scale is lower than at national scale, not zero.
A satisfaction with our years-long partnership led to more projects. And we continue with taking client's calls and making favors when client asks.
Questions we get asked directly
Should a small local outlet give up on subscriptions entirely, based on the LMC data?
No. The LMC finding is
Should a national outlet ignore advertising because Reuters Institute respondents rank it lower?
No. 64% still naming advertising as
What if our own numbers don't match either survey?
Trust your own numbers first. Both surveys describe averages across many publishers. Your specific market, competition level, and audience type will place you somewhere on